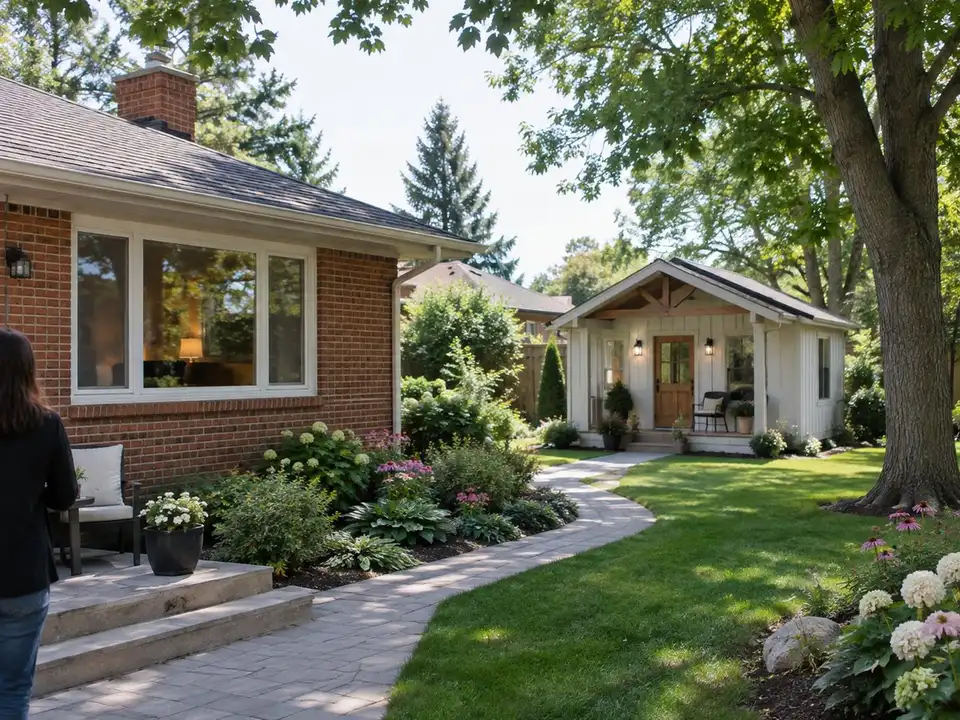
ReverseMortgageBurlington.ca sets out what Burlington homeowners 55 and older need to know before they build a garden suite. A garden suite in Burlington is a small, separate home in the backyard, for example for a parent, an adult child or a caregiver. What most people call a garden suite, the City treats as a detached additional residential unit (ARU) in an accessory building. The City allows one on most urban lots, and a reverse mortgage can pay to build it with no required monthly mortgage payments.
What happens when you first ask
You begin with the free estimate form. It asks three things: the age of the youngest owner, roughly what the home is worth, and any balance still owed. Your credit is not affected by asking for an estimate.
Next, the four lenders are weighed against each other, and the best deal for your house comes by email. Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada for your home. Family members can be copied on every email, which helps when a son or daughter will live in the suite. Three-way phone calls are easy to set up too.
Mention the garden suite plan in your first message, along with who will live in each home. That way the plan is part of how the lenders are compared from the beginning.
Nothing is signed early on. The estimate and that email are the first two of seven steps, and you can stop whenever you like. The one in-person meeting is with your own lawyer, shortly before closing.
What Burlington allows in a backyard
In the City’s rules, a garden suite falls under additional residential units (ARUs): it is the kind that sits in a separate building in the yard. The rules below come from the City’s ARU pages (City of Burlington).
How many units and how big
An urban residential lot with one detached house, semi-detached house or townhouse can have up to three additional units, with no rezoning needed. Only one of the three can be in a separate building in the yard.
That building can have up to 80 square metres of floor space, which is about 861 square feet. An existing garage or other accessory building can be converted.
Parking and lot coverage
The main home needs two parking spaces. The first additional unit needs none, and the second and third need one space each.
Tandem parking, with one car behind another, is allowed. Buildings on the lot can cover up to 45% of it, or more if the zone already allows more.
Where a garden suite is not allowed
Additional units are not allowed on properties served by a private well, cistern or septic system. Most of rural Burlington is in that group, so a garden suite is usually not possible there. The page on rural north Burlington covers reverse mortgages on country properties.
Permits, timing and fees
The registered owner has to make the application (City of Burlington).
The steps with the City
The process starts with a Pre-Building Approval application, which leads to a Zoning Clearance Certificate. The City says that takes about two weeks for interior work and three to four weeks when there is exterior work (City of Burlington Zoning FAQ). A garden suite is exterior work.
The building permit comes next. The City’s target is to review a complete application within 10 business days. A permit expires if the work hasn’t started within six months, so line up your builder and your money before applying.
Confirm fees with the City
The City has said zoning and building permit fees for these units are waived, but its incentive page says waivers ran until December 31, 2025. Ask the City what applies in 2026 before you set a budget. Education development charges, which go to the school boards, may apply to a detached unit and are not waived.
The City’s ARU Incentive Program, which offered forgivable loans for affordable rental units, closed on October 1, 2025 (City of Burlington).
An illustrative example: a $1,190,000 Burlington bungalow
Take an illustrative couple whose younger spouse is 65. Their detached bungalow on an urban lot appraises at $1,190,000, the September 2026 median sale price for a detached Burlington home (Cornerstone/ITSO, September 2026).
At 65, a borrower can get up to about 50.5% of the home’s value. On $1,190,000, that ceiling is about $602,000. They owe nothing on the home, so nothing is subtracted and the full $602,000 is available.
Their builder’s quote is $200,000 in this example, a figure used only to show the math. They take $200,000 and leave about $402,000 untouched. Interest is charged only on the $200,000.
You can run your own numbers in the Burlington reverse mortgage calculator.
What the lender needs to know
Tell Richard about the planned suite when you apply. The appraisal values your home as it stands on the day of the visit. A suite built later is not part of that first value.
If the suite is meant to give a son or daughter a place nearby, the page on giving a living inheritance in Burlington covers that side. If it is meant for a caregiver, the page on paying for home care in Burlington may help.
What it costs and how it is repaid
Advertised five-year fixed rates from the lenders ranged from 6.23% to 6.94% when checked on September 17, 2026. These rates apply across Ontario, including Burlington.
Before any building starts, the mortgage itself costs around $2,000 to $3,500 to arrange: an appraisal, a lender set-up fee, and $800 to $1,200 or so for your own lawyer.
Richard’s service costs you nothing, because the lender pays the brokerage after funding. The guide to reverse mortgage cost in Burlington shows every item.
No monthly mortgage payment is required. Your property taxes, home insurance and upkeep remain yours.
The balance climbs as interest is added to it. A suite can add to what the property is worth, and general price growth often makes up some or all of the interest too. On average, Canadian borrowers keep about half their equity.
Repayment waits until you sell, until the last borrower moves out permanently, or until the last borrower’s death. Keep the taxes, insurance and upkeep current and the debt is capped at what the home is worth on the open market at the time the mortgage becomes due. It’s typically called the no negative equity guarantee, and all four lenders offer it.
Early repayment is allowed at any time. In the early years a charge usually applies, either a percentage of the amount repaid or a few months’ interest, and it falls over time. Some lenders allow up to 10% of the balance each year with no charge.
What Richard does for you on this
- Estimates how much your home could provide toward the build
- Compares every reverse mortgage lender in Canada for your property
- All four lenders weighed, and the best deal for your home sent by email
- Copies your family on every email, which helps when they will live there
- Explains who can live where while the mortgage is in place
- Explains taking one amount now or drawing more later
- Tells the lender about the planned suite at the start
- Keeps track of the appraisal and each step through to closing
Burlington guides on this topic
- What does a reverse mortgage cost in Burlington?
- What are Burlington home prices in 2026?
- Burlington Property Tax for Seniors: What Helps in 2026
Sources
Figures checked October 15, 2026.
- City of Burlington, Additional residential units
- City of Burlington, Steps to build an additional residential unit
- City of Burlington, Additional residential unit incentive program
- City of Burlington, Zoning FAQ for additional residential units (revised February 2025)
- Cornerstone Association of REALTORS / ITSO, Burlington Monthly Indicators, September 2026