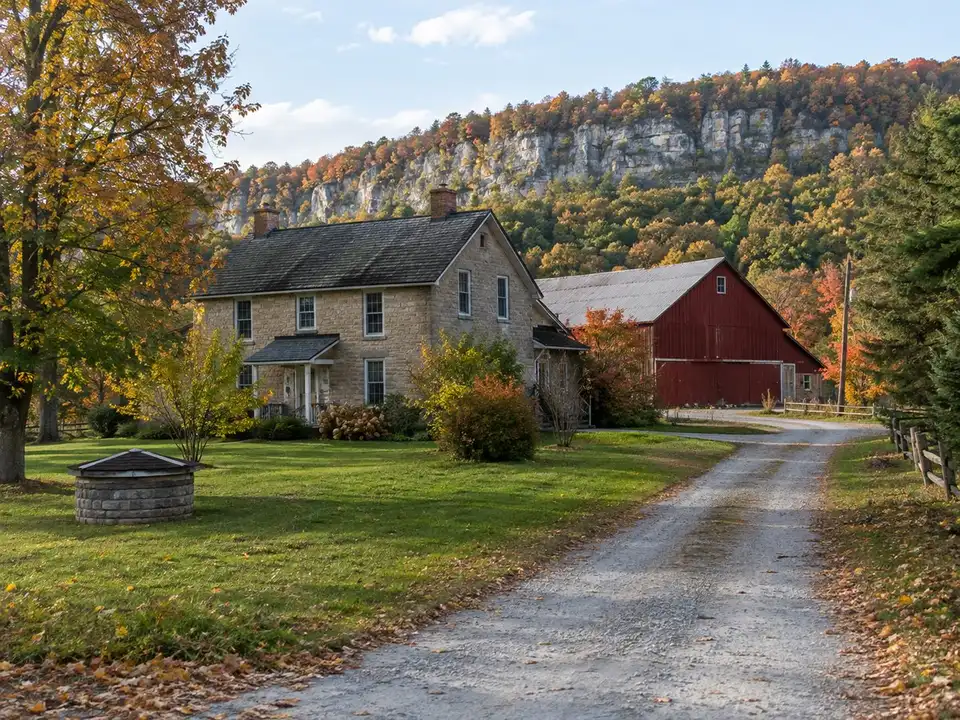
ReverseMortgageBurlington.ca explains how a rural Burlington reverse mortgage works for homeowners north of Highway 407, in and around Kilbride, Lowville and the Mount Nemo area. Country homes can qualify, but they get a closer look than a house on a city street. This page covers what is different about the land, what lenders and appraisers check, and how help reaches a homeowner on a rural road.
Where rural north Burlington is
Burlington’s main urban area lies south of the Parkway Belt and Highway 407. North of that line, and in north Aldershot, the land turns to farms, rural homes and conservation lands (Wikipedia).
The Niagara Escarpment runs through this part of the city. Mount Nemo Conservation Area sits on its edge, and the Bruce Trail follows the cliffs. Lowville sits in the Twelve Mile Creek valley beside Lowville Park, and Kilbride is a small hamlet in the same countryside.
Homes are spread out and varied
A rural property here can be an older stone farmhouse, a newer custom home on a few acres, or a modest bungalow on a country road. Some have outbuildings, long gravel drives and their own well and septic system. That variety is the reason no single price fits the area.
Burlington as a whole is half single-detached homes. The 2021 Census counted 36,760 of them, or 50.2% of occupied homes (Statistics Canada, 2021 Census Profile, Burlington).
What lenders look at on a rural property
Each reverse mortgage lender sets its own rules for rural properties. Some lend less on a country home than on a similar house in town, and some don’t lend on rural properties at all. The rules are not the same from one lender to the next, so the same home can get different answers.
The appraiser’s visit matters even more on a rural lot. The appraiser usually looks at the house, the well, the septic system, the access road and recent sales of similar homes nearby. Country homes sell less often, so finding close matches can take more work.
Only the home you live in qualifies. Lenders expect you to be there for at least half the year, so a weekend cottage or a rented-out property is not eligible.
Condition matters too. A home in serious disrepair can be turned down, while a repair that is already booked can sometimes be built into the mortgage. It helps to gather any records you have for the well, the septic system and the roof before the appraiser visits, and to know what work the house needs.
Why comparing every lender matters most here
On a country property, the lender you end up with can decide both whether you are approved and how much you get. Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada, which today means four: Bloom, Equitable Bank, HomeEquity Bank and Home Trust. You don’t pay for that work. The lender pays the brokerage, and only after the mortgage has funded.
Wells, septic and the extra unit question
A well and septic system change what you can do with the land. The City of Burlington does not allow additional residential units on properties served by a private well, cistern or septic system (City of Burlington). That covers most of rural Burlington.
For a family hoping to add a small home for a parent or an adult child, this rules out the usual route. On city-serviced lots, the garden suite option in Burlington is open, but on a septic lot it generally is not. Changing the main house is a separate question, covered under accessible home renovations.
Rural property tax is a little lower
Rural homes pay a slightly lower rate. For 2026, the City lists rural residential rates of 0.945872% and 0.948745%, against 1.015281% in the urban area (City of Burlington). On a home assessed at $500,000, that is about $4,729 to $4,744 instead of about $5,076.
Property taxes stay your bill with a reverse mortgage, along with home insurance and upkeep. Relief programs are in the guide to Burlington property tax for seniors.
An illustrative rural example
For example, an illustrative couple of 75 and 78 lives in a farmhouse near Lowville with its own well and septic. For this example the home appraises at $1,190,000, the same as Burlington’s September 2026 detached median (Cornerstone Association of REALTORS).
With the younger spouse at 75, the top of the age range is about 58% of the home’s value, or about $687,000. They still owe $85,000 on a HELOC (home equity line of credit), which is paid off first, leaving about $602,000. On a rural home, some lenders would offer less than that top figure.
They take $120,000 to start: part for a new roof and part for help at home. Interest is charged only on the money they take. There are no required monthly mortgage payments, but taxes, insurance and upkeep stay theirs.
How help reaches a rural homeowner
Help reaches a country address by email, phone and video call. Your estimate comes back on screen, and then you get every lender checked for your house and the best deal for your goals, emailed to you. Family can be copied on every email, and three-way calls are easy to set up.
The appraiser comes to the property. Apart from that visit, the one face-to-face step is independent legal advice with your own lawyer.
Plan on going to the lawyer’s office for it. It is usually one short appointment, and lenders normally ask for it to be face to face. If travel is truly hard for you, ask early: a lender may agree to a video call in its place.
The reverse mortgage cost guide for Burlington lists every one-time cost, and current values are in the guide to Burlington home prices.
Places in rural north Burlington
The help is the same wherever you live in rural north Burlington. These are some of the places it covers.
- Kilbride
- Lowville
- Mount Nemo area
- North Aldershot rural edge
Landmarks
- Mount Nemo Conservation Area
- Lowville Park
- Bruce Trail
- Niagara Escarpment
- Twelve Mile Creek valley
- Kilbride hamlet
- Royal Botanical Gardens
How the help reaches you in rural north Burlington
Everything with the broker happens by email, phone and video call, so a farm lane or a long drive into town makes no difference: the four lenders are still weighed against each other, and the best deal for your house comes by email. The appraiser comes to the property and usually looks at the home, the well, the septic and the access road. The one in-person meeting is with your own lawyer for independent legal advice, usually a short visit to a law office in Burlington or a nearby town.
What rural north Burlington properties are worth
Burlington detached homes sold for a median of $1,190,000 in September 2026. This is a city-wide figure; no rural-only figure is published, and country properties vary widely.
Source: Cornerstone Association of REALTORS, Burlington Monthly Indicators, September 2026
How rural north Burlington homeowners use a reverse mortgage
- Changing your home so you can stay: How Burlington homeowners 55 and older pay for walk-in showers, stair lifts and ramps from their home's value, with no monthly mortgage payments.
- Paying for help at home: Pay for private home care in Burlington from your home's value, with no required monthly mortgage payments.
- Helping family now: Give your children or grandchildren help now, such as a down payment, from your Burlington home's value while you keep living there.